


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Astronomia (294)
- Biologia (5119)
- Chemia (6540)
- Fizyka (3309)
- Matematyka (4574)
- Algebra (171)
- Analiza matematyczna (902)
- Filozofia matematyki (1)
- Geometria (237)
- Historia matematyki (57)
- Kombinatoryka, teoria grafów (67)
- Matematyka dyskretna (35)
- Matematyka stosowana (555)
- Optymalizacja (104)
- Podstawy matematyki (129)
- Statystyka, prawdopodobieństwo (296)
- Teoria grup (63)
- Teoria liczb (77)
- Topologia (66)
- Nauki ścisłe, ogólnie (503)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
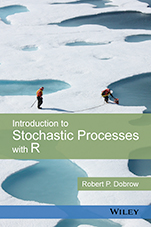
Introduction to Stochastic Processes with R
ISBN 9781118740651
Autor: Robert P. Dobrow
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 618,45 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9781118740651 |
ISBN10: |
1118740653 |
Autor: |
Robert P. Dobrow |
Oprawa: |
Hardback |
Rok Wydania: |
2016-04-19 |
Ilość stron: |
504 |
Wymiary: |
234x156 |
Tematy: |
PB |
An introduction to stochastic processes through the use of R
Introduction to Stochastic Processes with R is an accessible and well–balanced presentation of the theory of stochastic processes, with an emphasis on real–world applications of probability theory in the natural and social sciences. The use of simulation, by means of the popular statistical freeware R, makes theoretical results come alive with practical, hands–on demonstrations.
Written by a highly–qualified expert in the field, the author presents numerous examples from a wide array of disciplines, which are used to illustrate concepts and highlight computational and theoretical results. Developing readers problem–solving skills and mathematical maturity, Introduction to Stochastic Processes with R features:
Over 200 examples and 600 end–of–chapter exercises A tutorial for getting started with R, and appendices that contain review material in probability and matrix algebra Discussions of many timely and interesting supplemental topics including Markov chain Monte Carlo, random walk on graphs, card shuffling, Black–Scholes options pricing, applications in biology and genetics, cryptography, martingales, and stochastic calculus Introductions to mathematics as needed in order to suit readers at many mathematical levels A companion website that includes relevant data files as well as all R code and scripts used throughout the bookIntroduction to Stochastic Processes with R is an ideal textbook for an introductory course in stochastic processes. The book is aimed at undergraduate and beginning graduate–level students in the science, technology, engineering, and mathematics disciplines. The book is also an excellent reference for applied mathematicians and statisticians who are interested in a review of the topic.
Robert P. Dobrow, PhD, is Professor of Mathematics and Statistics at Carleton College. He has taught probability and stochastic processes for over 15 years and has authored numerous research papers in Markov chains, probability theory and statistics.
Preface xi
Acknowledgments xv
List of Symbols and Notation xvii
1 Introduction and Review 1
1.1 Deterministic and Stochastic Models 1
1.2 What is a Stochastic Process? 6
1.3 Monte Carlo Simulation 10
1.4 Conditional Probability 11
1.5 Conditional Expectation 19
Exercises 36
2 Markov Chains: First Steps 41
2.1 Introduction 41
2.2 Markov Chain Cornucopia 43
2.3 Basic Computations 53
2.4 LongTerm Behavior the Numerical Evidence 61
2.5 Simulation 67
2.6 Mathematical Induction∗ 71
Exercises 73
3 Markov Chains for the Long Term 79
3.1 Limiting Distribution 79
3.2 Stationary Distribution 83
3.3 Can You Find the Way to State a? 98
3.4 Irreducible Markov Chains 108
3.5 Periodicity 111
3.6 Ergodic Markov Chains 114
3.7 Time Reversibility 119
3.8 Absorbing Chains 124
3.9 Regeneration and the Strong Markov Property∗ 140
3.10 Proofs of Limit Theorems∗ 141
Exercises 152
4 Branching Processes 167
4.1 Introduction 167
4.2 Mean Generation Size 169
4.3 Probability Generating Functions 174
4.4 Extinction is Forever 178
Exercises 185
5 Markov Chain Monte Carlo 191
5.1 Introduction 191
5.2 MetropolisHastings Algorithm 197
5.3 Gibbs Sampler 208
5.4 Perfect Sampling∗ 216
5.5 Rate of Convergence: the Eigenvalue Connection∗ 222
5.6 Card Shuffling and Total Variation Distance∗ 224
Exercises 231
6 Poisson Process 235
6.1 Introduction 235
6.2 Arrival, Interarrival Times 239
6.3 Infinitesimal Probabilities 246
6.4 Thinning, Superposition 250
6.5 Uniform Distribution 256
6.6 Spatial Poisson Process 261
6.7 NonHomogeneous Poisson Process 265
6.8 Parting Paradox 267
Exercises 271
7 ContinuousTime
Markov Chains 277
7.1 Introduction 277
7.2 Alarm Clocks and Transition Rates 283
7.3 Infinitesimal Generator 286
7.4 LongTerm Behavior 297
7.5 Time Reversibility 308
7.6 Queueing Theory 316
7.7 Poisson Subordination 322
Exercises 329
8 Brownian Motion 337
8.1 Introduction 337
8.2 Brownian Motion and Random Walk 343
8.3 Gaussian Process 347
8.4 Transformations and Properties 351
8.5 Variations and Applications 363
8.6 Martingales 375
Exercises 386
9 A Gentle Introduction to Stochastic Calculus∗ 393
9.1 Introduction 393
9.2 Ito Integral 401
9.3 Stochastic Differential Equations 407
Exercises 420
Appendices 422
A Getting Started with R 423
B Probability Review 445
B.1 Discrete Random Variables 446
B.2 Joint Distribution 448
B.3 Continuous Random Variables 451
B.4 Common Probability Distributions 452
B.5 Limit Theorems 463
B.6 MomentGenerating Functions 464
C Summary of Probability Distributions 467
D Matrix Algebra Review 469
Problem Solutions 481
References 497
Index 501
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy