


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Astronomia (294)
- Biologia (5119)
- Chemia (6540)
- Fizyka (3309)
- Matematyka (4574)
- Algebra (171)
- Analiza matematyczna (902)
- Filozofia matematyki (1)
- Geometria (237)
- Historia matematyki (57)
- Kombinatoryka, teoria grafów (67)
- Matematyka dyskretna (35)
- Matematyka stosowana (555)
- Optymalizacja (104)
- Podstawy matematyki (129)
- Statystyka, prawdopodobieństwo (296)
- Teoria grup (63)
- Teoria liczb (77)
- Topologia (66)
- Nauki ścisłe, ogólnie (503)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
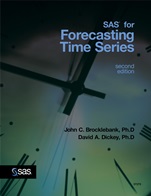
SAS for Forecasting Time Series
ISBN 9780471395669
Autor: John C. Brocklebank, David A. Dickey
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 606,90 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780471395669 |
ISBN10: |
0471395668 |
Autor: |
John C. Brocklebank, David A. Dickey |
Oprawa: |
Paperback |
Rok Wydania: |
2006-02-07 |
Numer Wydania: |
2nd Edition |
Ilość stron: |
424 |
Wymiary: |
279x210 |
Tematy: |
PB |
In this second edition of the indispensable SAS® for Forecasting Time Series, Brocklebank and Dickey show you how SAS performs univariate and multivariate time series analysis. Taking a tutorial approach, the authors focus on the procedures that most effectively bring results: the advanced procedures ARIMA, SPECTRA, STRATESPACE, and VARMAX. They demonstrate the interrelationship of SAS/ETS® procedures with a discussion of how the choice of a procedure depends on the data to be analyzed and the results desired. With this book, you will learn to model and forecast simple autoregressive and vector ARMA processes using the STATE–SPACE and VARMAX procedures. Other topics covered include detecting sinusoidal components in time series models, performing bivariate cross–spectral analysis, and comparing these frequency–based results with the time domain transfer function methodology.
New and updated examples in the second edition includeRetail sales with seasonalityARCH models for stock prices with changing volatilityVector autoregression and cointegration modelsIntervention analysis for product recall dataExpanded discussion of unit root tests and nonstationarityExpanded discussion of frequency domain analysis and cycles in dataData mining and forecasting with examples using SAS IntelliVisorUsing the HPF procedure to automatically generate forecasts for several time series in one step
Spis treści:
Preface.
Acknowledgments.
Chapter 1– Overview of Time Series.
Chapter 2– Simple Models: Autoregression.
Chapter 3– The General ARIMA Model.
Chapter 4– The ARIMA Model: Introductory Applications.
Chapter 5– The ARIMA Model: Special Applications.
Chapter 6– State Space Modeling.
Chapter 7– Spectral Analysis.
Chapter 8– Data Mining and Forecasting.
References.
Index.
<
b>Nota biograficzna:
John C. Brocklebank, Research and Development Director of Analytic Solutions at SAS, joined SAS in 1981 and has been a SAS user since 1978. Dr. Brocklebank received his Ph.D. in statistics and mathematics from North Carolina State University in 1981. He is often invited to conferences to speak about time series and statistical methods.
David A. Dickey is Professor of Statistics at North Carolina State University, where he teaches graduate courses in statistical methods and time series. An accomplished SAS user since 1976 and a prolific author, Dr. Dickey is the co–inventor of the Dickey–Fuller test used in SAS/ETS software. He received his Ph.D. in statistics from Iowa State University in 1976. He is a fellow of the American Statistical Association and a member of the Institute of Mathematical Statistics.
Okładka tylna:
In this second edition of the indispensable SAS® for Forecasting Time Series, Brocklebank and Dickey show you how SAS performs univariate and multivariate time series analysis. Taking a tutorial approach, the authors focus on the procedures that most effectively bring results: the advanced procedures ARIMA, SPECTRA, STRATESPACE, and VARMAX. They demonstrate the interrelationship of SAS/ETS® procedures with a discussion of how the choice of a procedure depends on the data to be analyzed and the results desired. With this book, you will learn to model and forecast simple autoregressive and vector ARMA processes using the STATE–SPACE and VARMAX procedures. Other topics covered include detecting sinusoidal components in time series models, performing bivariate cross–spectral analysis, and comparing these frequency–based results with the time domain transfer function methodology.
New and updated examples in the second edition includeRetail sales with seasonalityARCH models for stock prices with changing volatilit
yVector autoregression and cointegration modelsIntervention analysis for product recall dataExpanded discussion of unit root tests and nonstationarityExpanded discussion of frequency domain analysis and cycles in dataData mining and forecasting with examples using SAS IntelliVisorUsing the HPF procedure to automatically generate forecasts for several time series in one step
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy