


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
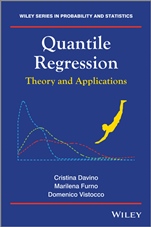
Quantile Regression: Theory and Applications
ISBN 9781119975281
Autor: Cristina Davino, Marilena Furno, Domenico Vistocco
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 451,50 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9781119975281 |
ISBN10: |
111997528X |
Autor: |
Cristina Davino, Marilena Furno, Domenico Vistocco |
Oprawa: |
Hardback |
Rok Wydania: |
2013-12-13 |
Ilość stron: |
276 |
Wymiary: |
241x166 |
Tematy: |
KF |
A guide to the implementation and interpretation of Quantile Regression models This book explores the theory and numerous applications of quantile regression, offering empirical data analysis as well as the software tools to implement the methods. The main focus of this book is to provide the reader with a comprehensivedescription of the main issues concerning quantile regression; these include basic modeling, geometrical interpretation, estimation and inference for quantile regression, as well as issues on validity of the model, diagnostic tools. Each methodological aspect is explored and followed by applications using real data. Quantile Regression: Presents a complete treatment of quantile regression methods, including, estimation, inference issues and application of methods. Delivers a balance between methodolgy and application, illustrating how Offers an overview of the recent developments in the quantile regression framework and why to use quantile regression in a variety of areas such as economics, finance and computing. Features a supporting website ( www.wiley.com/go/quantile—regression ) hosting datasets along with R, Stata and SAS software code. Researchers and PhD students in the field of statistics, economics, econometrics, social and environmental science and chemistry will benefit from this book.
Preface Acknowledgements Introduction 1 A Visual Introduction to Quantile Regression 1.1 The Essential Toolkit 1.1.1 Unconditional Mean, Unconditional Quantiles and Surroundings 1.1.2 Technical Insight: Quantiles as Solutions of a Minimization Problem 1.1.3 Conditional Mean, Conditional Quantiles and Surroundings 1.2 The Simplest QR Model: the Case of the Dummy Regressor 1.3 A Slightly More Complex QR Model: the Case of a Nominal Regressor 1.4 A Typical QR Model: the Case of a Quantitative Regressor 1.5 A Summary of Key Points References 2 Quantile Regression: Understanding How and Why 2.1 How and Why Quantile Regression Works 2.1.1 The General Linear Programming Problem 2.1.2 The Linear Programming Formulation for the QR Problem 2.1.3 Methods for Solving the Linear Programming Problem 2.2 A Set of Illustrative Artificial Data 2.2.1 Homogeneous Error Models 2.2.2 Heterogeneous Error Models 2.2.3 Dependent Data Error Models 2.3 How and Why to Work with Quantile Regression 2.3.1 QR for Homogeneous and Heterogeneous Models 2.3.2 QR Prediction Intervals 2.3.3 A Note on the Quantile Process 2.4 A Summary of Key Points References 3 Estimated Coefficients and Inference 3.1 Empirical Distribution of the Quantile Regression Estimator 3.1.1 The Case of Indipendent Identically Distributed Errors 3.1.2 The Case of Non–Identically Distributed Errors 3.1.3 The Case of Dependent Errors 3.2 Inference in Quantile Regression, the i.i.d. Case 3.3 Wald, Lagrange Multipliers, Likelihood Ratio Test 3.4 A Summary of Key Points References 4 Additional Tools for the Interpretation and Evaluation of the Quantile Regression Model 4.1 Data Pre–Processing 4.1.1 Explanatory Variable Transformations 4.1.2 Dependent Variable Transformations 4.2 Response Conditional Density Estimations 4.2.1 The Case of Different Scenario Simulations 4.2.2 The Case of the Response Variable Reconstruction 4.3 Validation of the Model 4.3.1 Goodness of Fit 4.3.2 Resampling Methods 4.4 A Summary of Key Points References 5 Models with Dependent and with Non–Identically Distributed Data 5.1 A Closer Look at the Scale Parameter, the i.i.d Case 5.1.1 Estimating the Variance of Quantile Regressions 5.1.2 Confidence Intervals and Hypothesis Testing on the Estimated Coefficients 5.1.3 Example for the i.i.d. Case 5.2 The Non Identically Distributed Case 5.2.1 Example for the Non Identically Distributed Case 5.2.2 Quick Ways to Test Equality of Coefficients across Quantiles in Stata 5.2.3 The Wage Equation Revisited 5.3 The Dependent Data Model 5.3.1 Example with Dependent Data 5.4 A Summary of Key Points 1 References 6 Additional Models 6.1 Nonparametric Quantile Regression 6.1.1 Local Polynomial Regression 6.1.2 Quantile Smoothing Splines 6.2 Nonlinear Quantile Regression 6.3 Censored Quantile Regression 6.4 Longitudinal data 6.5 Group Effect Quantile Regression 6.6 Binary Quantile Regression 6.7 A Summary of Key Points References A Quantile Regression and Surroundings Using R A.1 Loading Data A.1.1 Text Data A.1.2 Spreadsheet Data A.1.3 Files from Other Statistical Packages A.2 Exploring Data A.2.1 Graphical Tools A.2.2 Summary Statistics A.3 Modelling Data A.3.1 OLS Regression Analysis A.3.2 QR Regression Analysis A.4 Exporting Figures and Tables References B Quantile Regression Analysis and Surroundings Using SAS B.1 Loading Data B.1.1 Text Data B.1.2 Spreadsheet Data B.1.3 Files from Other Statistical Packages B.2 Exploring Data B.2.1 Graphical Tools B.2.2 Summary Statistics B.3 Modelling Data B.3.1 OLS Regression Analysis B.3.2 QR Regression Analysis B.4 Exporting Figures and Tables References C Quantile Regression and Surroundings Using Stata C.1 Loading Data C.1.1 Text Data C.1.2 Spreadsheet Data C.1.3 Files from Other Statistical Packages C.2 Exploring Data C.2.1 Graphical Tools C.2.2 Summary Statistics C.3 Modelling Data C.3.1 OLS Regression Analysis C.3.2 QR Regression Analysis C.4 Exporting Figures and Tables References Index
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy