


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
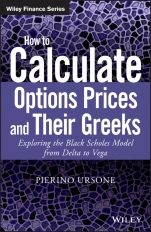
How to Calculate Options Prices and Their Greeks: Exploring the Black Scholes Model from Delta to Vega
ISBN 9781119011620
Autor: Pierino Ursone
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 279,30 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9781119011620 |
ISBN10: |
1119011620 |
Autor: |
Pierino Ursone |
Oprawa: |
Hardback |
Rok Wydania: |
2015-04-24 |
Ilość stron: |
224 |
Wymiary: |
238x160 |
Tematy: |
KF |
Praise for How to Calculate Options Prices and Their Greeks
"Clearly written and easy to read. The book covers all the essential topics and has many very interesting approaches. In my current job, liaising with derivatives trading houses and as a former options trader, I can conclude that the book demonstrates that the Netherlands still functions as an expert area for the options business. How to Calculate Options Prices and Their Greeks has everything in it to become the standard reference book on options. Highly recommended!"
Rogier Elsenburg, Head of Benelux & France Huxley Banking & Financial Services
"Pierino Ursone′s How to Calculate Options Prices and their Greeks provides a long overdue, comprehensive, and at the same time digestible update to the literature exploring options pricing and strategy. His writing is clear, concise, and straight–forward; unlocking the Holy Grail for the inexperienced and even the most experienced options trader. Ursone liberally illustrates each chapter with graphics and acknowledges the Black Scholes Model′s mathematical and theoretical nderpinnings in plain, straight–forward language that makes new understanding of the complexity of options trading possible for both the novice and the expert. Ursone′s thorough explanation of the practical application of first and second order greeks goes beyond the simplistic, two–dimensional strategies most traders will find when trying to educate themselves about options. He uses his vast experience and knowledge to act as expert, trader, tactician, and teacher, guiding readers through the markets and allowing them to look inside as they could never before."
Matt Daen, Options Specialist
"Finally a holistic guide to options! This practical guide is essential for those seeking an understanding of option derivatives. Beyond merely informative, this handbook for the practitioner details the finer points of the use of options as tools for trading and price–risk management. No professional should be without it."
Dr Tom James, Commodity Market Expert & Author
"An easy to read handbook for investors who wish to thoroughly understand, trade and manage an options portfolio. Pierino explains the characteristics and behaviour of options in a pragmatic way, coming from a trading perspective. Very helpful for private and professional investors with a goal of running a complex derivatives portfolio in a controlled manner."
Jelle Elzinga, Former Global Management Committee Optiver Group
Preface ix
Chapter 1 Introduction 1
Chapter 2 The Normal Probability Distribution 7
Standard deviation in a financial market 8
The impact of volatility and time on the standard deviation 8
Chapter 3 Volatility 11
The probability distribution of the value of a Future after one year of trading 11
Normal distribution versus log–normal distribution 11
Calculating the annualised volatility traditionally 15
Calculating the annualised volatility without 17
Calculating the annualised volatility applying the 16% rule 19
Variation in trading days 20
Approach towards intraday volatility 20
Historical versus implied volatility 23
Chapter 4 Put Call Parity 25
Synthetically creating a Future long position, the reversal 29
Synthetically creating a Future short position, the conversion 30
Synthetic options 31
Covered call writing 34
Short note on interest rates 35
Chapter 5 Delta 37
Change of option value through the delta 38
Dynamic delta 40
Delta at different maturities 41
Delta at different volatilities 44
20 80 Delta region 46
Delta per strike 46
Dynamic delta hedging 47
The at the money delta 50
Delta changes in time 53
Chapter 6 Pricing 55
Calculating the at the money straddle using
Black and Scholes formula 57
Determining the value of an at the money straddle 59
Chapter 7 Delta II 61
Determining the boundaries of the delta 61
Valuation of the at the money delta 64
Delta distribution in relation to the at the money straddle 65
Application of the delta approach, determining the delta of a call spread 68
Chapter 8 Gamma 71
The aggregate gamma for a portfolio of options 73
The delta change of an option 75
The gamma is not a constant 76
Long term gamma example 77
Short term gamma example 77
Very short term gamma example 78
Determining the boundaries of gamma 79
Determining the gamma value of an at the money straddle 80
Gamma in relation to time to maturity,
volatility and the underlying level 82
Practical example 85
Hedging the gamma 87
Determining the gamma of out of the money options 89
Derivatives of the gamma 91
Chapter 9 Vega 93
Different maturities will display different volatility regime changes 95
Determining the vega value of at the money options 96
Vega of at the money options compared to volatility 97
Vega of at the money options compared to time to maturity 99
Vega of at the money options compared to the underlying level 99
Vega on a 3–dimensional scale, vega vs maturity and vega vs volatility 101
Determining the boundaries of vega 102
Comparing the boundaries of vega with the boundaries of gamma 104
Determining vega values of out of the money options 105
Derivatives of the vega 108
Vomma 108
Chapter 10 Theta 111
A practical example 112
Theta in relation to volatility 114
Theta in relation to time to maturity 115
Theta of at the money options in relation to the underlying level 117
Determining the boundaries of theta 118
The gamma theta relationship 120
Theta on a 3–dimensional scale, theta vs maturity and theta vs volatility 125
Determining the theta value of an at the money straddle 126
Determining theta values of out of the money options 127
Chapter 11 Skew 129
Volatility smiles with different times to maturity 131
Sticky at the money volatility 133
Chapter 12 Spreads 135
Call spread (horizontal) 135
Put spread (horizontal) 137
Boxes 138
Applying boxes in the real market 139
The Greeks for horizontal spreads 140
Time spread 146
Approximation of the value of at the money spreads 148
Ratio spread 149
Chapter 13 Butterfly 155
Put call parity 158
Distribution of the butterfly 159
Boundaries of the butterfly 161
Method for estimating at the money butterfly values 163
Estimating out of the money butterfly values 164
Butterfly in relation to volatility 165
Butterfly in relation to time to maturity 166
Butterfly as a strategic play 166
The Greeks of a butterfly 167
Straddle strangle or the Iron fly 171
Chapter 14 Strategies 173
Call 173
Put 174
Call spread 175
Ratio spread 176
Straddle 177
Strangle 178
Collar (risk reversal, fence) 178
Gamma portfolio 179
Gamma hedging strategies based on Monte Carlo scenarios 180
Setting up a gamma position on the back of prevailing kurtosis in the market 190
Excess kurtosis 191
Benefitting from a platykurtic environment 192
The mesokurtic market 193
The leptokurtic market 193
Transition from a platykurtic environment towards a leptokurtic environment 194
Wrong hedging strategy: Killergamma 195
Vega convexity/Vomma 196
Vega convexity in relation to time/Veta 202
Index 205
PIERINO URSONE has extensive option trading experience. He began his career as a Market Maker with Optiver, an international market maker that trades on all of the world′s major financial markets. Afterwards, Ursone ran his own option trading company on the Dutch options exchange in Amsterdam, and after nine years in equity options, he entered the Energy commodity market, trading options on a proprietary basis.
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy