


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
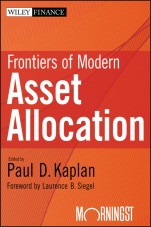
Frontiers of Modern Asset Allocation
ISBN 9781118115060
Autor: Paul D. Kaplan, Laurence B. Siegel
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 449,40 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9781118115060 |
ISBN10: |
1118115066 |
Autor: |
Paul D. Kaplan, Laurence B. Siegel |
Oprawa: |
Hardback |
Rok Wydania: |
2012-01-27 |
Ilość stron: |
384 |
Wymiary: |
230x164 |
Tematy: |
KF |
Praise for Frontiers of Modern Asset Allocation "This is a book where theory meets practice and results in innovation. Some of Paul′s research challenges commonly used asset–allocation methodologies and offers investors interesting alternatives. A most interesting read." — Bruno Solnik , Professor of finance, Hong Kong University of Science and Technology and HEC Paris "The foundations of MPT, though solid, are desperately in need of updating to reflect modern market dynamics. Paul does exactly that while taking time to shatter myths along the way. Read this book and you will have in your possession modern tools masterfully applied to asset allocation relevant to today′s investors." — Rodney N. Sullivan , CFA, Editor, Financial Analysts Journal, CFA Institute "This book by Paul Kaplan is a most unusual, and worthwhile, mix of practitioner wisdom and academic rigour, topped with some excellent interviews and debates; highly recommended." — Dr. Steve Satchell , Fellow, Trinity College, University of Cambridge "Paul Kaplan′s state–of–the–art research on asset allocation has been instrumental in resolving many of the issues that face practitioners. In Frontiers of Modern Asset Allocation , Paul brings much of his work together to walk the reader through the evolution of asset allocation toward a better understanding of its state in today′s markets." — Brian Singer , CFA, Head of Global Macro Strategies, William Blair & Company, LLC "The breadth and depth of the articles in this book suggest that Paul Kaplan has been thinking about markets for about as long as markets have existed." — From the Foreword by Laurence B. Siegel In 1952, the economist Harry Markowitz introduced a now–commonplace concept: investors can construct an "efficient portfolio" by investing in diverse securities combined to maximize expected returns while minimizing expected volatility. Markowitz revolutionized investing. Ever since, the idea of asset allocation has been the bedrock of constructing portfolios. The pursuit of finding a portfolio′s sweet spot—the optimal area where various asset classes work in conjunction to provide the most returns for the least risk—has given rise to an incredible body of research and range of products.
Foreword xi Introduction xxiii A Note on Expected Return and Geometric Mean xxv Acknowledgments xxxi PART ONE Equities CHAPTER 1 Purity of Purpose: How Style–Pure Indexes Provide Useful Insights 7 CHAPTER 2 Investing in Europe with Style: Why Investors in Europe Would Benefit From Constructing Portfolios Through the Prism of Style 15 CHAPTER 3 Why Fundamental Indexation Might—or Might Not—Work 21 CHAPTER 4 The Fundamental Debate: Two Experts Square Off on the Big Issues Surrounding Fundamentally Weighted Indexes 39 CHAPTER 5 Collared Weighting: A Hybrid Approach to Indexing 51 CHAPTER 6 Yield to Investors? A Practical Approach to Building Dividend Indexes 63 CHAPTER 7 Holdings–Based and Returns–Based Style Models 71 CHAPTER 8 Estimates of Small Stock Betas Are Much Too Low 103 CHAPTER 9 A Macroeconomic Model of the Equity Risk Premium 117 PART TWO Fixed Income, Real Estate, and Alternatives CHAPTER 10 Good and Bad Monetary Economics, and Why Investors Need to Know the Difference 133 CHAPTER 11 Inflation, Gilt Yields, and Economic Policy 143 CHAPTER 12 Reverse Mean–Variance Optimization for Real Estate Asset–Allocation Parameters 147 CHAPTER 13 The Long and Short of Commodity Indexes 157 CHAPTER 14 Less Alpha and More Beta Than Meets the Eye 175 CHAPTER 15 Venture Capital and its Role in Strategic Asset Allocation 179 PART THREE Crashes and Fat Tails CHAPTER 16 One–and–a–Quarter Centuries of Stock Market Drawdowns 193 CHAPTER 17 Stock Market Bubbles and Crashes: A Global Historical and Economic Perspective 199 CHAPTER 18 De´ ja` Vu All Over Again 211 CHAPTER 19 De´ ja` Vu Around the World 223 CHAPTER 20 Getting a Read on Risk: A Discussion with Roger Ibbotson, George Cooper, and Benoˆıt Mandelbrot on the Crisis and Risk Models 239 PART FOUR Doing Asset Allocation CHAPTER 21 Does Asset–Allocation Policy Explain 40 Percent, 90 Percent, or 100 Percent of Performance? 253 CHAPTER 22 Asset–Allocation Models Using the Markowitz Approach 267 CHAPTER 23 Asset Allocation with Annuities for Retirement Income Management 275 CHAPTER 24 MPT Put Through the Wringer: A Debate Between Steven Fox and Michael Falk 303 CHAPTER 25 Updating Monte Carlo Simulation for the Twenty–First Century 311 CHAPTER 26 Markowitz 2.0 325 CHAPTER 27 What Does Harry Markowitz Think? A Discussion with Harry Markowitz and Sam Savage 351 Afterword 367 About the Author 375 Index 377
Paul D. Kaplan is quantitative research director at Morningstar Europe and is responsible for the quantitative methodologies behind Morningstar′s fund analysis, indexes, advisor tools, and other services. Dr. Kaplan conducts research on investment style analysis, performance and risk measurement, asset allocation, retirement–income planning, portfolio construction, index methodologies, and alternative investments. He led the development of quantitative methodologies behind the Morningstar Rating for funds (Morningstar′s star rating), the Morningstar Style Box, and the Morningstar family of indexes. Many of Dr. Kaplan′s research papers have been published in professional books and publications such as the Financial Analysts Journal , the Journal of Portfolio Management , the Journal of Wealth Management , the Journal of Investing , the Journal of Performance Measurement , the Journal of Indexes , and the Handbook of Equity Style Management . He received the 2008 Graham and Dodd Award and won a Graham and Dodd Award of Excellence in 2000.
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy