


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
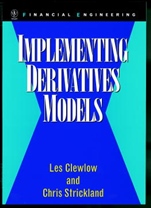
Implementing Derivative Models
ISBN 9780471966517
Autor: Les Clewlow, Chris Strickland
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 627,90 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780471966517 |
ISBN10: |
0471966517 |
Autor: |
Les Clewlow, Chris Strickland |
Oprawa: |
Hardback |
Rok Wydania: |
1998-04-29 |
Ilość stron: |
330 |
Wymiary: |
261x179 |
Tematy: |
KF |
Implementing Derivatives Models Les Clewlow and Chris Strickland Derivatives markets, particularly the over–the–counter market in complex or exotic options, are continuing to expand rapidly on a global scale, However, the availability of information regarding the theory and applications of the numerical techniques required to succeed in these markets is limited. This lack of information is extremely damaging to all kinds of financial institutions and consequently there is enormous demand for a source of sound numerical methods for pricing and hedging. Implementing Derivatives Models answers this demand, providing comprehensive coverage of practical pricing and hedging techniques for complex options. Highly accessible to practitioners seeking the latest methods and uses of models, including
∗ The Binomial Method
∗ Trinomial Trees and Finite Difference Methods
∗ Monte Carlo Simulation
∗ Implied Trees and Exotic Options
∗ Option Pricing, Hedging and Numerical Techniques for Pricing Interest Rate Derivatives
∗ Term Structure Consistent Short Rate Models
∗ The Heath, Jarrow and Morton Model
Implementing Derivatives Models is also a potent resource for financial academics who need to implement, compare, and empirically estimate the behaviour of various option pricing models. Finance/Investment
Spis treści:
The Binomial Methods.
Finite Difference Models.
The Monte Carlo Method.
Implied Trees .
Yield Curve Fitting Trees.
Applications to Exotic Options.
Conclusion.
Nota biograficzna:
Les Clewlow and Chris Strickland both hold positions at the Financial Options Research Centre, Warwick University, UK, at the School of Finance and Economics, University of Technology Sydney, Australia, and the Instituto de Estudios Superiores de Administración, Caracas, Venezuela. They are also both principals of Lacima Consultants specialising in derivati
ves pricing and risk management education and software.
Okładka tylna:
Implementing Derivatives Models Les Clewlow and Chris Strickland Derivatives markets, particularly the over–the–counter market in complex or exotic options, are continuing to expand rapidly on a global scale, However, the availability of information regarding the theory and applications of the numerical techniques required to succeed in these markets is limited. This lack of information is extremely damaging to all kinds of financial institutions and consequently there is enormous demand for a source of sound numerical methods for pricing and hedging. Implementing Derivatives Models answers this demand, providing comprehensive coverage of practical pricing and hedging techniques for complex options. Highly accessible to practitioners seeking the latest methods and uses of models, including
∗ The Binomial Method
∗ Trinomial Trees and Finite Difference Methods
∗ Monte Carlo Simulation
∗ Implied Trees and Exotic Options
∗ Option Pricing, Hedging and Numerical Techniques for Pricing Interest Rate Derivatives
∗ Term Structure Consistent Short Rate Models
∗ The Heath, Jarrow and Morton Model
Implementing Derivatives Models is also a potent resource for financial academics who need to implement, compare, and empirically estimate the behaviour of various option pricing models. Finance/Investment
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy