


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
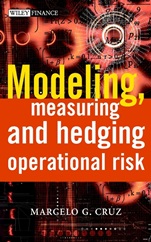
Modeling, Measuring and Hedging Operational Risk
ISBN 9780471515609
Autor: Marcelo G. Cruz
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 279,30 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780471515609 |
ISBN10: |
0471515604 |
Autor: |
Marcelo G. Cruz |
Oprawa: |
Hardback |
Rok Wydania: |
2002-01-22 |
Ilość stron: |
346 |
Wymiary: |
265x166 |
Tematy: |
KF |
Dr Marcelo Cruz is rightfully acknowledged as a world expert in the quantification of operational risk. He has set out to produce a book that is comprehensive yet also comprehensible to non–mathematicians – and is to be congratulated for succeeding in this aim. This book should be regarded as essential reading for all professional risk managers, irrespective of their particular lens of perception." Brendan Young, Chairman, Operational Risk Research Forum
"As a technically trained analyst, Marcelo Cruz summarizes a wide range of mathematical techniques. As an experienced capital markets trader and risk manager, he provides real world examples of their relevance for operational risk. This will be a common reference work in the field for years to come." David M. Rowe, Ph.D., Group Executive Vice President for Risk Management Sun Gard Trading and Risk Systems
Operational risk is an important, yet little explored, area within risk management. The need to model and measure the risks arising from operational errors and to allocate capital against them will be soon become a regulatory requirement for financial institutions. In this book, Marcelo Cruz provides a quantitative look at the subject, presenting several mathematical models that can be used and adapted to measure, manage and hedge operational risk.
Based on the author′s extensive experience, the book maps out state–of–the–art mathematical and statistical techniques that can be used to model operational risk. In addition, the book describes a variety of appropriate models that can be applied to specific structures or areas, including operational risk database modeling, stochastic models, statistical distributions for frequency and severity, extreme value theory, operational VaR models, artificial intelligence models, dynamic multifactor models, Bayesian analysis, Monte Carlo simulation, stress test/ scenario analysis, real options, state–space models and the Kalma
n filter, Markovian stochastic models and others. These models have been tested with real data in real operational events. Based on this experience, numerous examples are sited throughout.
Modeling, Measuring and Hedging Operational Risk provides a complete quantitative reference for all those involved in modeling and managing operational risk as well as for those involved with developing hedging products for operational risk within insurance companies and derivatives houses.
Spis treści:
Introduction
PART I: DATABASE MODELING
Database Modeling
PART II: STOCHASTIC MODELING
Severity Distributions
Extreme Value Theory
Frequency Distributions
The Operational Risk VaR
Stochastic Processes in Operational Risk
PART III: CAUSAL MODELS
Causal Models : Applying Econometrics and Time Series Statistics to Operational Risk
Non–Linear Models in Operational Risk
Bayesian Techniques in Operational Risk
PART IV: OPERATIONAL RISK MANAGEMENT
Operational Risk Reporting, Control and Management
– Stress Tests and Scenario Analysis in Operational Risk
PART V: HEDGING OPERATIONAL RISK
Operational Risk Derivatives
Developing an OR Hedging Program
PART VI: OPERATIONAL RISK REGULATORY CAPITAL
Operational Risk Regulatory Capital
PART VII: MEASURING "OTHER RISKS" –
FOREGONE REVENUE MEASUREMENT MODELS
An Enterprise–Wide Model for Measuring Reputational Risk
– Measuring Concentration (or Key Personnel) Risk
– Using Real Options in Modeling and Measuring Operational and ′Other′ Risks
APPENDIX –
Valuing Networks –
Understanding the basics of e–ventures valuation
Nota biograficzna:
DR MARCELO CRUZ is currently CEO and founder of RiskMaths, a boutique consultancy specialising in the development and validation of complex mathematical and statistical models for risk management, financial asset pricing, capital a
llocation and financial management strategy. RiskMaths has a particular focus on operational risk modeling, measurement and hedging with a client base that includes large global financial institutions and financial regulators. Dr Cruz participates in the regulatory discussions on the new Basel Accord and was a member of the Industry Technical Working Group that proposed the changes on the regulatory capital charges to the Basel Committee on Banking Supervision. Prior to RiskMaths, Dr Cruz worked as a senior executive in the risk management area for various global investment banks and led the development of operational risk quantitative modeling for a large European bank. He has also worked as a senior derivatives trader and structurer.
Dr Cruz regularly writes for several academic and industry journals and magazines including The Journal of Risk, RISK magazine, the Financial Times and Derivatives Week. He has also contributed to several risk management books, the most recent of which include ′Extremes and Integrated Risk Management′, ′Managing Hedge Fund Risk′, ′Mastering Risk, Volume 2′ and ′Advances in Operational Risk: Firmwide Issues for Financial Institutions′. Dr Cruz is a sought–after speaker in risk management conferences and seminars and had lectured in many countries in Europe, Asia and the Americas as well as leading universities in Europe, USA and Latin America. He holds a Ph.D. in Mathematical Finance, a M.Sc., M.B.A., Diploma and a B.Sc. in Economics.
Okładka tylna:
"Dr Marcelo Cruz is rightfully acknowledged as a world expert in the quantification of operational risk. He has set out to produce a book that is comprehensive yet also comprehensible to non–mathematicians – and is to be congratulated for succeeding in this aim. This book should be regarded as essential reading for all professional risk managers, irrespective of their particular lens of perception."
Brendan Young, Chairman, Operational Risk Research Forum
"As a technically trained analyst, Marcelo Cruz summarizes a wide range of mathematical techniques. As an experienced capital markets trader and risk manager, he provides real world examples of their relevance for operational risk. This will be a common reference work in the field for years to come." David M. Rowe, Ph.D., Group Executive Vice President for Risk Management Sun Gard Trading and Risk Systems
Operational risk is an important, yet little explored, area within risk management. The need to model and measure the risks arising from operational errors and to allocate capital against them will be soon become a regulatory requirement for financial institutions. In this book, Marcelo Cruz provides a quantitative look at the subject, presenting several mathematical models that can be used and adapted to measure, manage and hedge operational risk.
Based on the author′s extensive experience, the book maps out state–of–the–art mathematical and statistical techniques that can be used to model operational risk. In addition, the book describes a variety of appropriate models that can be applied to specific structures or areas, including operational risk database modeling, stochastic models, statistical distributions for frequency and severity, extreme value theory, operational VaR models, artificial intelligence models, dynamic multifactor models, Bayesian analysis, Monte Carlo simulation, stress test/ scenario analysis, real options, state–space models and the Kalman filter, Markovian stochastic models and others. These models have been tested with real data in real operational events. Based on this experience, numerous examples are sited throughout.
Modeling, Measuring and Hedging Operational Risk provides a complete quantitative reference for all those involved in modeling and managing operational risk as well as for those involved with developing hedging products for
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy