


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)



Informacje szczegółowe o książce
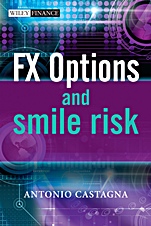
FX Options and Smile Risk
ISBN 9780470754191
Autor: Antonio Castagna
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 408,45 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780470754191 |
ISBN10: |
0470754192 |
Autor: |
Antonio Castagna |
Oprawa: |
Hardback |
Rok Wydania: |
2009-12-04 |
Ilość stron: |
320 |
Wymiary: |
251x173 |
Tematy: |
KF |
The FX options market represents one of the most liquid and strongly competitive markets in the world, and features many technical subtleties that can seriously harm the uninformed and unaware trader.
This book is a unique guide to running an FX options book from the market maker perspective. Striking a balance between mathematical rigour and market practice and written by experienced practitioner Antonio Castagna, the book shows readers how to correctly build an entire volatility surface from the market prices of the main structures.
Starting with the basic conventions related to the main FX deals and the basic traded structures of FX options, the book gradually introduces the main tools to cope with the FX volatility risk. It then goes on to review the main concepts of option pricing theory and their application within a Black–Scholes economy and a stochastic volatility environment. The book also introduces models that can be implemented to price and manage FX options before examining the effects of volatility on the profits and losses arising from the hedging activity.
Coverage includes:how the Black–Scholes model is used in professional trading activitythe most suitable stochastic volatility modelssources of profit and loss from the Delta and volatility hedging activityfundamental concepts of smile hedgingmajor market approaches and variations of the Vanna–Volga methodvolatility–related Greeks in the Black–Scholes modelpricing of plain vanilla options, digital options, barrier options and the less well known exotic optionstools for monitoring the main risks of an FX options’ book
The book is accompanied by a CD Rom featuring models in VBA, demonstrating many of the approaches described in the book.
Spis treści:
Preface.
Notation and Acronyms.
1 The FX Market.
1.1 FX rates and spot contracts.
1.2 Outright and
FX swap contracts.
1.3 FX option contracts.
1.4 Main traded FX option structures.
2 Pricing Models for FX Options.
2.1 Principles of option pricing theory.
2.2 The black–scholes model.
2.3 The Heston Model.
2.4 The SABR model.
2.5 The mixture approach.
2.6 Some considerations about the choice of model.
3 Dynamic Hedging and Volatility Trading.
3.1 Preliminary considerations.
3.2 A general framework.
3.3 Hedging with a constant implied volatility.
3.4 Hedging with an updating implied volatility.
3.5 Hedging Vega.
3.6 Hedging Delta, Vega, Vanna and Volga.
3.7 The volatility smile and its phenomenology.
3.8 Local exposures to the volatility smile.
3.9 Scenario hedging and its relationship with Vanna–Volga hedging.
4 The Volatility Surface.
4.1 General definitions.
4.2 Criteria for an efficient and convenient representation of the volatility surface.
4.3 Commonly adopted approaches to building a volatility surface.
4.4 Smile interpolation among strikes: the Vanna–Volga approach.
4.5 Some features of the Vanna–Volga approach.
4.6 An alternative characterization of the Vanna–Volga approach.
4.7 Smile interpolation among expiries: implied volatility term structure.
4.8 Admissible volatility surfaces.
4.9 Taking into account the market butterfly.
4.10 Building the volatility matrix in practice.
5 Plain Vanilla Options.
5.1 Pricing of plain vanilla options.
5.2 Market–making tools.
5.3 Bid/ask spreads for plain vanilla options.
5.4 Cutoff times and spreads.
5.5 Digital options.
5.6 American plain vanilla options.
6 Barrier Options.
6.1 A taxonomy of barrier options.
6.2 Some relationships of barrier option prices.
6.3 Pricing for barrier options in a BS economy.
6.4 Pricing formulae for barrier options.
6.5 One–touch (rebate) and no–touch options.
6.6 DoubleR
11;barrier options.
6.7 Double–no–touch and double–touch options.
6.8 Probability of hitting a barrier.
6.9 Greek calculation.
6.10 Pricing barrier options in other model settings.
6.11 Pricing barriers with non–standard delivery.
6.12 Market approach to pricing barrier options.
6.13 Bid/ask spreads.
6.14 Monitoring frequency.
7 Other Exotic Options.
7.1 Introduction.
7.2 At–expiry barrier options.
7.3 Window barrier options.
7.4 First–then and knock–in–knock–out barrier options.
7.5 Auto–quanto options.
7.6 Forward start options.
7.7 Variance swaps.
7.8 Compound, asian and lookback options.
8 Risk Management Tools and Analysis.
8.1 Introduction.
8.2 Implementation of the LMUV model.
8.3 Risk monitoring tools.
8.4 Risk analysis of plain vanilla options.
8.5 Risk analysis of digital options.
9 Correlation and FX Options.
9.1 Preliminary considerations.
9.2 Correlation in the BS setting.
9.3 Contracts depending on several FX spot rates.
9.4 Dealing with correlation and volatility smile.
9.5 Linking volatility smiles.
References.
Index.
Nota biograficzna:
Antonio Castagna is currently partner and co–founder of the consulting company Iason ltd, providing support to financial institutions for the design of models to price complex derivatives and to measure a wide range of risks, including credit and liquidity. Antonio graduated in Finance from LUISS University, Rome, in 1995 with a thesis on American options and the numerical procedures for their valuation. He began his career in investment banking in IMI Bank, Luxemborug, as a financial analyst in the Risk Control Department before moving to Banca IMI, Milan, first as a market maker of cap/floors and swaptions, before setting up the FX options desk and running the book of plain vanilla and exotic options
on the major currencies, whilst also being responsible for the entire FX volatility trading.
Antonio has written a number of papers on credit derivatives, managing of exotic options risks and volatility smiles. He is often invited to academic and post–graduate courses.
Okładka tylna:
The FX options market represents one of the most liquid and strongly competitive markets in the world, and features many technical subtleties that can seriously harm the uninformed and unaware trader.
This book is a unique guide to running an FX options book from the market maker perspective. Striking a balance between mathematical rigour and market practice and written by experienced practitioner Antonio Castagna, the book shows readers how to correctly build an entire volatility surface from the market prices of the main structures.
Starting with the basic conventions related to the main FX deals and the basic traded structures of FX options, the book gradually introduces the main tools to cope with the FX volatility risk. It then goes on to review the main concepts of option pricing theory and their application within a Black–Scholes economy and a stochastic volatility environment. The book also introduces models that can be implemented to price and manage FX options before examining the effects of volatility on the profits and losses arising from the hedging activity.
Coverage includes:how the Black–Scholes model is used in professional trading activitythe most suitable stochastic volatility modelssources of profit and loss from the Delta and volatility hedging activityfundamental concepts of smile hedgingmajor market approaches and variations of the Vanna–Volga methodvolatility–related Greeks in the Black–Scholes modelpricing of plain vanilla options, digital options, barrier options and the less well known exotic optionstools for monitoring the main risks of an FX
options’ book
The book is accompanied by a CD Rom featuring models in VBA, demonstrating many of the approaches described in the book.
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy