


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)



Informacje szczegółowe o książce
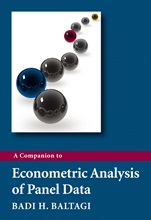
A Companion to Econometric Analysis of Panel Data
ISBN 9780470744031
Autor: Badi H. Baltagi
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 260,40 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780470744031 |
ISBN10: |
0470744030 |
Autor: |
Badi H. Baltagi |
Oprawa: |
Paperback |
Rok Wydania: |
2009-03-06 |
Ilość stron: |
308 |
Wymiary: |
244x170 |
Tematy: |
KC |
This book is a companion to Baltagi’s (2008) leading graduate econometrics textbook on panel data entitled Econometric Analysis of Panel Data, 4th Edition.
The book guides the student of panel data econometrics by solving exercises in a logical and pedagogical manner, helping the reader understand, learn and apply panel data methods. It is also a helpful tool for those who like to learn by solving exercises and running software to replicate empirical studies. It works as a complementary study guide to Baltagi (2008) and also as a stand alone book that builds up the reader’s confidence in working out difficult exercises in panel data econometrics and applying these methods to empirical work.
The exercises start by providing some background information on partitioned regressions and the Frisch–Waugh–Lovell theorem. Then it goes through the basic material on fixed and random effects models in a one–way and two–way error components models: basic estimation, test of hypotheses and prediction. This include maximum likelihood estimation, testing for poolability of the data, testing for the significance of individual and time effects, as well as Hausman′s test for correlated effects. It also provides extensions of panel data techniques to serial correlation, spatial correlation, heteroskedasticity, seemingly unrelated regressions, simultaneous equations, dynamic panel models, incomplete panels, measurement error, count panels, rotating panels, limited dependent variables, and non–stationary panels.
The book provides several empirical examples that are useful to applied researchers, illustrating them using Stata and EViews showing the reader how to replicate these studies. The data sets are provided on the Wiley web site: www.wileyeurope.com/college/baltagi.
Spis treści:
Preface.
1 Partitioned Regression an
d the Frisch–Waugh–Lovell Theorem.
Exercises.
1.1 Partitioned regression.
1.2 The Frisch–Waugh–Lovell theorem.
1.3 Residualing the constant.
1.4 Adding a dummy variable for the ith observation.
1.5 Computing forecasts and forecast standard errors.
2 The One–way Error Component Model.
2.1 The One–way Fixed Effects Model.
Exercises.
2.1 One–way fixed effects regression.
2.2 OLS and GLS for fixed effects.
2.3 Testing for fixed effects.
2.2 The One–way Random Effects Model.
Exercises.
2.4 Variance–covariance matrix of the one–way random effects model.
2.5 Fuller and Battese (1973) transformation for the one–way random effects model.
2.6 Unbiased estimates of the variance components: the one–way model.
2.7 Feasible unbiased estimates of the variance components: the one–way model.
2.8 Gasoline demand in the OECD.
2.9 System estimation of the one–way model: OLS versus GLS.
2.10 GLS is a matrix weighted average of between and within.
2.11 Efficiency of GLS compared to within and between estimators.
2.12 Maximum likelihood estimation of the random effects model.
2.13 Prediction in the one–way random effects model.
2.14 Mincer wage equation.
2.15 Bounds for s2 in a one–way random effects model.
2.16 Heteroskedastic fixed effects models.
3 The Two–way Error Component Model.
3.1 The Two–way Fixed Effects Model.
Exercise.
3.1 Two–way fixed effects regression.
3.2 The Two–way Random Effects Model.
Exercises.
3.2 Variance–covariance matrix of the two–way random effects model.
3.3 Fuller and Battese (1973) transformation for the two–way random effects model.
3.4 Unbiased estimates of the variance components: the two–way model.
3.5 Feasible unbiased estim
ates of the variance components: the two–way model.
3.6 System estimation of the two–way model: OLS versus GLS.
3.7 Prediction in the two–way random effects model.
3.8 Variance component estimation under misspecification.
3.9 Bounds for s2, in a two–way random effects model.
3.10 Nested effects.
3.11 Three–way error component model.
3.12 A mixed error component model.
3.13 Productivity of public capital in private production.
4 Test of Hypotheses Using Panel Data.
4.1 Tests for Poolability of the Data.
Exercises.
4.1 Chow (1960) test.
4.2 Roy (1957) and Zellner (1962) test.
4.2 Tests for Individual and Time Effects.
Exercises.
4.3 Breusch and Pagan (1980) Lagrange multiplier test.
4.4 Locally mean most powerful one–sided test.
4.5 Standardized Honda (1985) test.
4.6 Standardized King and Wu (1997) test.
4.7 Conditional Lagrange multiplier test: random individual effects.
4.8 Conditional Lagrange multiplier test: random time effects.
4.9 Testing for poolability using Grunfeld’s data.
4.10 Testing for random time and individual effects using Grunfeld’s data.
4.3 Hausman’s Test for Correlated Effects.
Exercises.
4.11 Hausman (1978) test based on a contrast of two estimators.
4.12 Hausman (1978) test based on an artificial regression.
4.13 Three contrasts yield the same Hausman test.
4.14 Testing for correlated effects in panels.
4.15 Hausman’s test as a Gauss–Newton regression.
4.16 Hausman’s test using Grunfeld’s data.
4.17 Relative efficiency of the between estimator with respect to the within estimator.
4.18 Hausman’s test using Munnell’s data.
4.19 Currency Union and Trade.
5 Heteroskedasticity and Serial Correlation.
5.1 Heteroskedastic Error Component Model.
Exercises.
5.1 Heteroskedastic individual eff
ects.
5.2 An alternative heteroskedastic error component model.
5.3 An LM test for heteroskedasticity in a one–way error component model.
5.2 Serial Correlation in the Error Component Model.
Exercises.
5.4 AR(1) process.
5.5 Unbiased estimates of the variance components under the AR(1) model.
5.6 AR(2) process.
5.7 AR(4) process for quarterly data.
5.8 MA(1) process.
5.9 MA(q) process.
5.10 Prediction in the serially correlated error component model.
5.11 A joint LM test for serial correlation and random individual effects.
5.12 Conditional LM test for serial correlation assuming random individual effects.
5.13 An LM test for first–order serial correlation in a fixed effects model.
5.14 Gasoline demand example with first–order serial correlation.
5.15 Public capital example with first–order serial correlation.
6 Seemingly Unrelated Regressions with Error Components.
Exercises.
6.1 Seemingly unrelated regressions with one–way error component disturbances.
6.2 Unbiased estimates of the variance components of the one–way SUR model.
6.3 Special cases of the SUR model with one–way error component disturbances.
6.4 Seemingly unrelated regressions with two–way error component disturbances.
6.5 Unbiased estimates of the variance components of the two–way SUR model.
6.6 Special cases of the SUR model with two–way error component disturbances.
7 Simultaneous Equations with Error Components.
7.1 Single Equation Estimation.
Exercises.
7.1 2SLS as a GLS estimator.
7.2 Within 2SLS and between 2SLS.
7.3 Within 2SLS and between 2SLS as GLS estimators.
7.4 Error component two–stage least squares.
7.5 Equivalence of several EC2SLS estimators.
7.6 Hausman test based on FE2SLS vs EC2SLS.
7.2 System Estimation.
Exercises.
7.7 3SLS as a GLS estimator.
7.8 Within 3S
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy