


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)



Informacje szczegółowe o książce
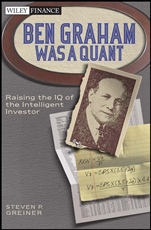
Ben Graham Was a Quant: Raising the IQ of the Intelligent Investor
ISBN 9780470642078
Autor: Steven P. Greiner
Wydawca: Wiley
Dostępność: 3-6 tygodni
Cena: 248,85 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780470642078 |
ISBN10: |
0470642076 |
Autor: |
Steven P. Greiner |
Oprawa: |
Hardback |
Rok Wydania: |
2011-04-15 |
Ilość stron: |
352 |
Wymiary: |
241x163 |
Tematy: |
KF |
Praise for Ben Graham Was a Quant
"If you are looking for a straightforward explanation of quantitative investment techniques, this is the book for you. Whether you are an MBA student, a CFA candidate, or just a curious investor interested in the world of the quant, this is a great primer on the subject."
—Dan Cardell
CQA, Wintrust Wealth Management
"When everybody is bashing quants, it is refreshing to hear that Ben Graham was a quant! Read this book to understand what a quant is and how you can apply Ben Graham′s thinking using quant factors to build a factor model and a portfolio using the Graham factors. A very good read for those who want to learn basic quantitative techniques to manage their own portfolios. This book will walk you through how to build Ben Graham factors and then create a factor model to create your own portfolio."
—Pankaj N. Patel
Managing Director, Quantitative Equity Research, Credit Suisse Group AG
"This highly eclectic book is a must–read complement to conventional course readings in equity portfolio management for any aspiring quantitative finance master of science student."
—R. Douglas Martin
Professor of Statistics, Director of Computational
Finance Program, University of Washington
Spis treści:
Preface.
Introduction: The Birth of the Quant.
Characterizing the Quant.
Active versus Passive Investing.
Chapter 1: Desperately Seeking Alpha.
The Beginnings of the Modern Alpha Era.
Important History of Investment Management.
Methods of Alpha Searching.
Chapter 2: Risky Business.
Experienced versus Exposed Risk.
The Black Swan: A Minor ELE Event—Are Quants to Blame?
Active versus Passive Risk.
Other Risk Measures: VAR, CVAR, and ETL.
Summary.
Chapter 3: Beta Is Not Sharpe Enough.
Back to Beta.
Beta and Volatility.
The Way to a Better “Beta”: Introducing the g–Factor.<
br>Tracking Error: The Deviant Differential Measurer.
Summary.
Chapter 4: Mr. Graham, I Give You Intelligence.
Fama–French Equation.
The Graham Formula.
Factors for Use in Quant Models.
Momentum: Increasing Investor Interest.
Volatility as a Factor in Alpha Models.
Chapter 5: Modeling Pitfalls and Perils.
Data Availability, Look–Ahead, and Survivorship Biases.
Building Models One Can Trust.
Scenario, Out–Of–Sample, and Shock Testing.
Data Snooping and Mining.
Statistical Significance and Other Fascinations.
Choosing an Investment Philosophy.
Growth, Value, Quality.
Investment Consultant as Dutch Uncle.
Where are the Relative Growth Managers?
Chapter 6: Testing the Graham “Crackers”...er, Factors.
The First Tests: Sorting.
Time–Series Plots.
The Next Tests: Scenario Analysis.
Chapter 7: Building Models from Factors.
Surviving Factors.
Weighting the Factors.
The Art versus Science of Modeling.
Time–Series of Returns.
Other Conditional Information.
The Final Model.
Other Methods of Measuring Performance: Attribution Analysis Via Brinson and Risk Decomposition.
Regression of the Graham Factors with Forward Returns.
Chapter 8: Building Portfolios from Models.
The Deming Way: Benchmarking Your Portfolio.
Portfolio Construction Issues.
Using an Online Broker: Fidelity, E∗Trade, TD–Ameritrade, Schwab, Interactive Brokers, and TradeStation.
Working with A Professional Investment Management System: Bloomberg, Clarify, and Factset.
Chapter 9: Barguments: The Anti–Dementia Bacterium.
The Colossal Non–Failure of Asset Allocation.
The Stock Market as a Class of Systems.
Stochastic Portfolio Theory: An Introduction.
Portfolio Optimization: The Layman’s Perspective.
Tax–Efficient Optimization.
Summary.
Chapter 10: Past and Futu
re View.
Why did Global Contagion and Meltdown Occur?
Fallout of Crises.
The Rise of the Multi–National State Owned Enterprises.
The Emerged Markets.
The Future Quant.
Notes.
Acknowledgments.
About the Author.
Index.
Nota biograficzna:
Steven P. Greiner, Ph.D., has served as the senior quantitative strategist and portfolio manager for Allegiant Asset Management (now wholly owned by PNC Capital Advisors) and was a member of its Investment Committee. Prior to this, he was a senior quantitative strategist for large capitalization investments at Harris Investment Management. He has more than twenty years of quantitative and modeling experience. Currently, Dr. Greiner is the head of Risk Research for FactSet Research Systems. He received a BS in mathematics and chemistry from the University of Buffalo, an MS and PhD in physical chemistry from the University of Rochester, and attained postdoctoral experience from the Free University Berlin, Department of Physics.
Okładka tylna:
Praise for Ben Graham Was a Quant
"If you are looking for a straightforward explanation of quantitative investment techniques, this is the book for you. Whether you are an MBA student, a CFA candidate, or just a curious investor interested in the world of the quant, this is a great primer on the subject."
—Dan Cardell
CQA, Wintrust Wealth Management
"When everybody is bashing quants, it is refreshing to hear that Ben Graham was a quant! Read this book to understand what a quant is and how you can apply Ben Graham′s thinking using quant factors to build a factor model and a portfolio using the Graham factors. A very good read for those who want to learn basic quantitative techniques to manage their own portfolios. This book will walk you through how to build Ben Graham factors and then create a factor model to create your own portfolio."
—Pankaj N. Patel
Managing Director, Quantita
tive Equity Research, Credit Suisse Group AG
"This highly eclectic book is a must–read complement to conventional course readings in equity portfolio management for any aspiring quantitative finance master of science student."
—R. Douglas Martin
Professor of Statistics, Director of Computational
Finance Program, University of Washington
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy