


Wydawcy
Katalog tematyczny
- Archeologia (109)
- Ekonomia, finanse, business (13704)
- Filozofia (1445)
- Historia (3040)
- Języki i językoznawstwo (2356)
- Lifestyle, hobby i rozrywka (475)
- Medycyna (9704)
- Nauki humanistyczne (4)
- Nauki o Ziemi i środowisku (2638)
- Nauki ścisłe (20412)
- Nauki społeczne (8486)
- Nauki techniczne (13450)
- Prawo (1696)
- Publikacje informacyjne i interdyscyplinarne (1288)
- Religia i wierzenia (917)
- Technika komputerowa (4067)
- Zdrowie, relacje międzyludzkie i rozwój osobisty (657)





Informacje szczegółowe o książce
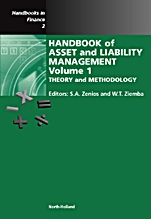
Handbook of Asset and Liability Management: Theory and Methodology
ISBN 9780444508751
Autor: Zenios, Stavros A.Ziemba, William T.
Wydawca: Elsevier
Dostępność: 3-6 tygodni
Cena: 804,30 zł
Przed złożeniem zamówienia prosimy o kontakt mailowy celem potwierdzenia ceny.
ISBN13: |
9780444508751 |
ISBN10: |
0444508759 |
Autor: |
Zenios, Stavros A.Ziemba, William T. |
Oprawa: |
Hardback |
Rok Wydania: |
2006-07-17 |
Tematy: |
KFCF |
This first volume of the Handbook of Asset and Liability Management presents the theories and methods supporting models that align a firm's operations and tactics with its uncertain environment. Detailing the symbiosis between optimization tools and financial decision-making, its original articles cover term and volatility structures, interest rates, risk-return analysis, dynamic asset allocation strategies in discrete and continuous time, the use of stochastic programming models, bond portfolio management, and the Kelly capital growth theory and practice. They effectively set the scene for Volume Two by showing how the management of risky assets and uncertain liabilities within an integrated, coherent framework remains the core problem for both financial institutions and other business enterprises as well.
*Each volume presents an accurate survey of a sub-field of finance
*Fills a substantial gap in this field
*Broad in scope
Volume 1.
Theory and Methodology.
Preface to Volumes A and B. 1.Enterprise-Wide Asset and Liability Management:Issues, Institutions and Models (D. Rosen & S. Zenios). 2. Term and volatility structures (R.J-.B. Wets & S. Bianchi). 3. Protecting investors against changes in interest rates (O. de la Grandville). 4. Risk-return analysis (H. Markowitz & E. van Dijk). 5. Dynamic Asset allocation and strategies (G. Infanger). 6. Stochastic programming models (R. Kouwenberg & S.A. Zenios). 7. Bond portfolio management via stochastic programming (M. Bertochhi, J. Dupacova, V. Moriggia). 8. Pertubation methods for dynamic portfolio allocation problems (G. Chacko & K. Neumar). 9. The Kelly criterion in blackjack, sport betting and the stock market (E. O’Thorpe). 10. Capital growth theory and practice (L. MacLean & W. T. Ziemba).
Koszyk
Książek w koszyku: 0 szt.
Wartość zakupów: 0,00 zł
Informacje


Kontakt
Gambit
Centrum Oprogramowania
i Szkoleń Sp. z o.o.
Al. Pokoju 29b/22-24
31-564 Kraków
Siedziba Księgarni
ul. Kordylewskiego 1
31-542 Kraków
+48 12 410 5991
+48 12 410 5987
+48 12 410 5989
Subskrypcje
Administratorem danych osobowych jest firma Gambit COiS Sp. z o.o. Na podany adres będzie wysyłany wyłącznie biuletyn informacyjny.
Autoryzacja płatności

Informacje na temat autoryzacji płatności poprzez PayU.
© Copyright 2012: GAMBIT COiS Sp. z o.o. Wszelkie prawa zastrzeżone.
Projekt i wykonanie: Alchemia Studio Reklamy